The Power of Compound Interest in Investing
By William · Swift Penguin · Educational content · Not financial advice
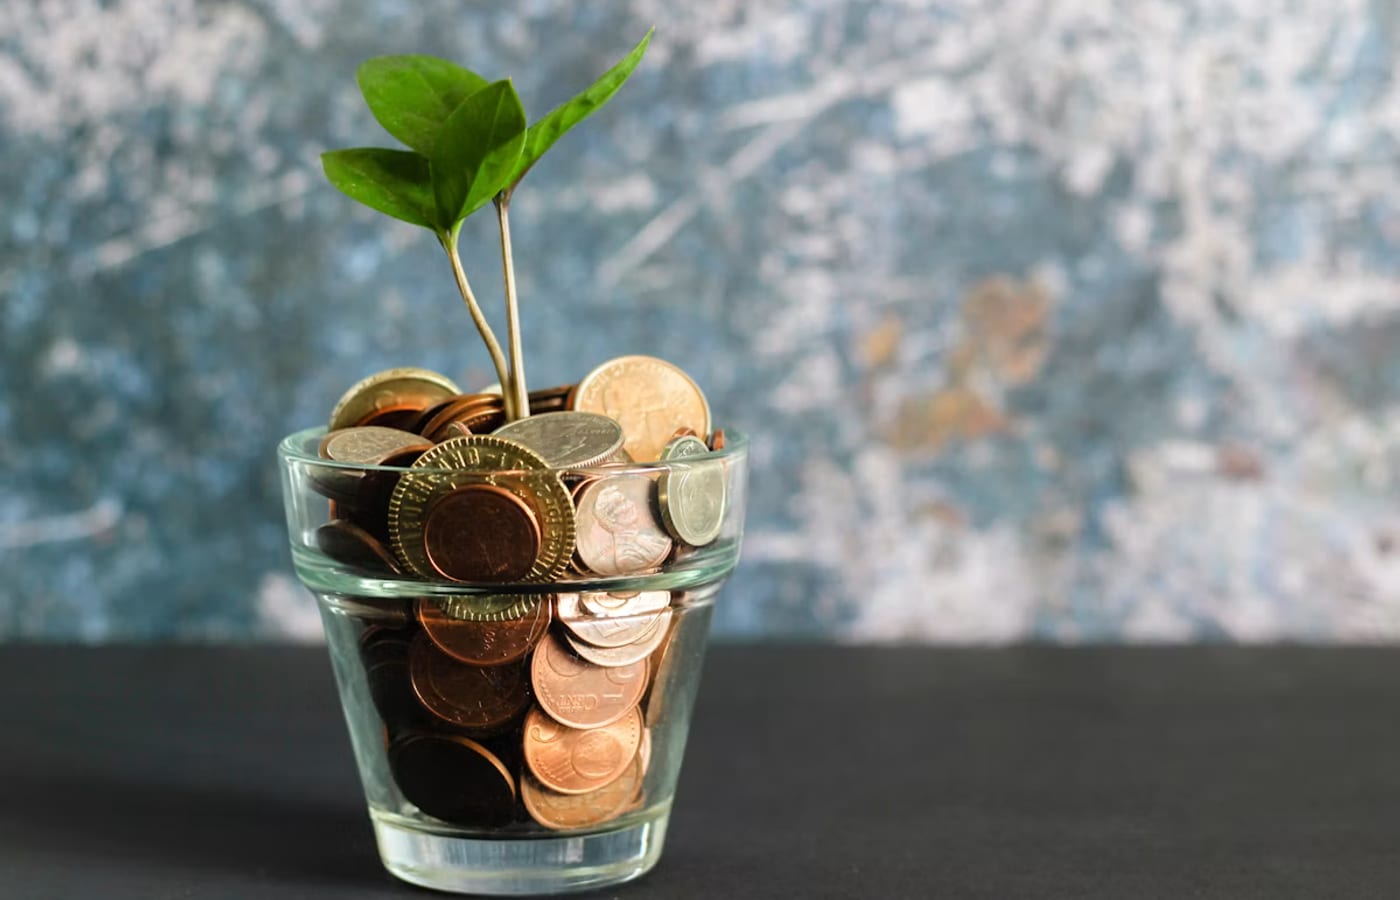
Compound interest is growth on top of prior growth — your gains start making their own little gains. Over decades that can get silly, but only if you stay invested and keep feeding the thing.
See why time beats timing, walk through a 30-year contribution example, and learn the habits (reinvest, stay consistent) that make compounding actually show up in your account.
Simple vs compound growth
Simple interest: you earn on your original money only. Compound interest: you earn on everything — original money plus all past gains.
Year one? Barely noticeable. Year thirty? Often the difference between “I saved a lot” and “the portfolio did most of the work.”
In investing, “compounding” usually means staying invested and reinvesting dividends and gains — not a special bank product.
An example
Hypothetical only (not a forecast): $500 a month at a steady 8% annual return. After 30 years you’ve put in $180,000. The account would be worth about $745,000. That extra ~$565k is compounding doing the work — real markets bounce around and don’t deliver a fixed 8%.
Start ten years earlier with the same contributions under the same assumption? You’re looking at roughly $1.7 million. Time is the biggest lever in the formula.
Run your own numbers with a compound growth calculator — then ask whether raising contributions is easier than chasing a riskier return assumption.
What usually breaks compounding
Stopping contributions after a crash (the moment shares are on sale).
High fees and unnecessary trading that skim the snowball every year.
Pulling money out for lifestyle upgrades the market hasn’t permanently funded yet.
The takeaway
Start as early as you can. Even small amounts matter if they compound long enough.
Stay consistent. Monthly contributions beat trying to time the perfect entry.
Reinvest everything. Dividends and gains left in the account are what build the snowball.
Next steps
Concepts stick when you apply them. Open a related calculator, run your own numbers, and — if you’re still learning execution — practice with paper trades before increasing real size. Browse more guides or the full set of free trading tools.
Free tool
Compound Growth Projector
Project ending balance with contributions, return rate, and time — plus inflation view, $100k–$1M milestones, and what-if levers (save more vs earn more vs stay longer). Chart and year table included.
Other free tools
- Stock Market Simulator — Practice trading with fake money.
- Trading 212 Portfolio Charts — Connect T212 and flex your P&L.
- Crypto Prices & Charts — Live quotes + historic charts.
Put this into practice
Run the numbers on our free tools, or paper trade before you risk real money.
This is educational content, not financial advice. Investing carries risk — you can lose money. Do your own research and consider a qualified advisor for personal decisions.